How FRS 102 Lease Accounting Will Impact the UK Construction Industry
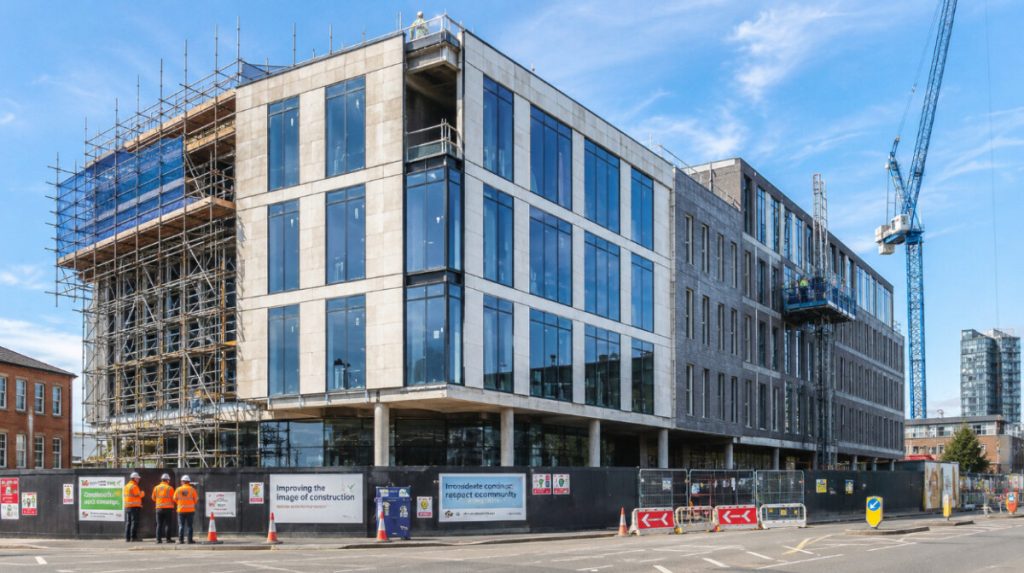
FRS 102 lease accounting changes are set to become a major reporting issue for the UK construction industry. For many contractors, developers, civil engineering firms, housebuilders, plant hire operators and specialist subcontractors, leasing is not a side issue. It is part of how projects get delivered.
Construction businesses lease cranes, excavators, telehandlers, scaffolding, site cabins, welfare units, vans, trucks, offices, yards, storage facilities, temporary power equipment, surveying tools and specialist machinery. They may also operate through multiple project sites, joint arrangements, subsidiaries and subcontractor relationships. That makes lease accounting under FRS 102 more than a technical finance update. It is a change that could affect balance sheets, bank covenants, project reporting, tendering, cash flow analysis and management decisions.
For a sector already dealing with tight margins, high insolvency risk, labour pressures and volatile project pipelines, getting lease accounting right will matter.
What Is Changing Under FRS 102?
The Financial Reporting Council’s Periodic Review 2024 amendments to FRS 102 leases apply for accounting periods beginning on or after 1 January 2026, with early adoption permitted. The amendments include major changes to lease accounting, especially for lessees.
Under the new model, many leases that were previously treated as operating leases will come onto the balance sheet. ACCA explains that lessees will recognise a right-of-use asset and a lease liability on the balance sheet under the revised FRS 102 requirements.
KPMG summarises the direction of the change clearly: existing operating leases under FRS 102 will be brought on balance sheet, with a lease liability recognised for future lease payments and a right-of-use asset recognised for the lessee’s right to use the asset.
In simple terms, construction firms will no longer be able to treat many significant leases as purely off-balance-sheet rental costs. The commercial arrangement may be the same, but the accounting presentation changes.
The Scale of the Sector Makes the Change Important
Construction is a major part of the UK economy. The Office for National Statistics publishes annual construction statistics covering output, new orders, firms, employment, insolvencies and construction price indices, underlining the scale and economic importance of the sector.
At the same time, construction firms often operate under financial pressure. A recent report in The Times noted that the sector has faced weak housebuilding, infrastructure delays and a high level of insolvencies, with 3,827 construction insolvencies recorded in the past year.
That context matters. When margins are tight, balance sheet changes can affect how banks, insurers, bonding providers, suppliers and clients assess a contractor’s financial strength.
Right-of-Use Assets and Lease Liabilities Explained
Under the revised FRS 102 lease accounting model, a lessee will generally recognise two things for many leases.
The first is a right-of-use asset. This represents the company’s right to use the leased item during the lease term.
The second is a lease liability. This represents the obligation to make future lease payments.
For example, if a construction company leases a fleet of vans for four years, it may need to recognise an asset representing the right to use those vans and a liability representing the present value of future lease payments.
The same concept may apply to longer-term leases of plant, offices, depots or equipment.
Instead of recording a simple operating lease rental expense, the company may record depreciation on the right-of-use asset and interest on the lease liability. AccountingWEB notes that the previous operating lease expense will be replaced by depreciation and interest under the new model.
The Balance Sheet Impact for Contractors
The most obvious impact will be larger balance sheets. Many construction companies will show more assets and more liabilities.
This can affect key financial measures, including:
- Net assets
- Gearing
- Debt ratios
- Current and non-current liabilities
- Return on capital employed
- Interest cover
- EBITDA
- Covenant calculations
- Credit assessments
- Bonding capacity
This does not necessarily mean the business has become riskier. The lease obligations already existed commercially. The new rules simply make many of them more visible.
However, perception matters. A contractor with significant plant leases may suddenly appear more indebted in its financial statements. Banks and surety providers may need to understand the accounting change so that it does not distort credit assessments.
The Profit and Loss Impact
The profit and loss account may also change. Under the old operating lease model, a construction business typically recognised lease payments as rental expense over the lease term.
Under the revised model, many lease costs will be split between depreciation and interest. This can change profit presentation.
EBITDA may increase because lease expenses are no longer treated in the same way as operating costs. However, depreciation and finance costs will increase.
For businesses that report project performance, this creates a practical issue. Construction companies often track profitability by job, site, division or contract. If lease costs are now split differently in the accounts, management reporting may need to be redesigned so project managers still understand the true cost of plant and equipment used on each job.
Plant Hire and Equipment Leasing: The Core Challenge
Plant and equipment are at the heart of the construction lease accounting issue. Contractors often use hired or leased equipment because ownership is not always practical. A project may need a tower crane for 18 months, a fleet of excavators for nine months, or specialist lifting equipment for only one phase of work.
The accounting question is whether the arrangement is a lease, a service, a short-term hire, or a contract containing both lease and non-lease components.
For example, a simple one-week hire of a small item may be treated differently from a multi-year lease of a dedicated machine. A contract that includes both equipment and an operator may need closer analysis. A service contract that gives the contractor control over a specific asset may also need review.
ICAEW notes that FRS 102 reporters will need to consider whether a contract is, or contains, a lease.
For construction companies with hundreds of hire agreements, that assessment can become a major administrative exercise.
Short-Term Leases and Practical Exemptions
Not every lease will necessarily be recognised on the balance sheet. The revised model includes practical reliefs, including exemptions for certain short-term and low-value leases.
This will be important in construction because many site hire arrangements are short-term. A contractor may hire equipment for days, weeks or a few months depending on project need.
However, businesses should not assume that every hire contract qualifies for an exemption. The lease term, renewal pattern, economic substance and contract terms all matter. A series of short rolling arrangements may need more careful assessment than a one-off hire.
The safest approach is to create a clear lease accounting policy and apply it consistently.
Embedded Leases in Construction Contracts
Some of the hardest leases to identify are not labelled as leases at all.
Construction firms may enter into service contracts that include the right to use specific assets. Examples might include dedicated site accommodation, specialist access equipment, waste processing assets, temporary energy systems, or plant supplied under a broader package arrangement.
If the contractor controls the use of an identified asset for a period of time, the contract may contain a lease component.
This is where finance teams need help from procurement, operations and project managers. The accounting team may not know whether a contract gives the company control over a specific asset unless the operational team explains how the arrangement works in practice.
Project Costing Could Become More Complicated
Construction firms need accurate project costing. They must know what each job costs, what margin it is generating and whether the project is on budget.
Lease accounting changes can complicate this because statutory accounting and project management reporting may no longer align neatly.
For example, a project manager may think of a telehandler cost as a weekly hire charge. The finance system may record depreciation and interest for a right-of-use asset. Both views may be useful, but they serve different purposes.
Businesses may need parallel reporting:
- Statutory reporting for FRS 102 compliance
- Management reporting for project costing and tender analysis
- Cash reporting for actual lease and hire payments
- Operational reporting for plant utilisation
The goal is to comply with FRS 102 without losing practical visibility over site-level costs.
Tendering and Pricing Decisions
Lease accounting can also affect tendering. Contractors need to understand the full cost of plant, equipment and temporary site assets when pricing work.
If lease costs are not allocated properly, bids may be underpriced. That can be dangerous in a low-margin industry.
For example, if a company uses leased plant across multiple jobs, the cost needs to be allocated fairly. If one project uses the equipment heavily but another project absorbs the accounting charge, project profitability becomes misleading.
Tender teams should work with finance to ensure plant and lease costs are reflected realistically in pricing models.
Bank Covenants, Bonding and Credit Risk
Construction companies often rely on bank facilities, invoice finance, asset finance, performance bonds, parent company guarantees and supplier credit. These arrangements may include financial covenants or credit assessments based on accounting numbers.
FRS 102 lease changes could affect those numbers.
Higher recognised lease liabilities may affect debt measures. Higher EBITDA may affect earnings-based measures. Increased interest expense may affect interest cover.
KPMG specifically highlights the need for businesses to assess wider impacts such as KPIs, covenants and remuneration schemes when lease accounting changes are introduced.
Construction firms should speak to lenders and bonding providers early. Covenant definitions may need to be reviewed so that accounting changes do not create unintended consequences.
Impact on Subcontractors and Specialist Trades
The lease accounting change will not only affect large contractors. Specialist subcontractors may also be exposed.
Groundworks contractors, roofing firms, scaffolding businesses, mechanical and electrical contractors, fit-out companies, demolition specialists and civil engineering subcontractors often rely on leased equipment, vehicles and temporary site assets.
Smaller businesses may be less prepared because they often rely on spreadsheets, external accountants and informal asset tracking. A subcontractor with multiple vans, equipment leases and yard leases may still face a meaningful accounting change.
The key issue is not company size. It is lease exposure.
Why This Matters So Much in Construction
The construction industry is unusually exposed to lease accounting because it relies heavily on access to assets without always owning them. Buying every item of plant, every vehicle and every temporary site asset outright would tie up huge amounts of capital. Leasing and hiring give contractors flexibility, especially when project needs change from site to site.
That flexibility is commercially useful, but it creates accounting complexity.
A medium-sized contractor may lease or hire:
- Excavators and diggers
- Tower cranes and mobile cranes
- Telehandlers and forklifts
- Dumpers and rollers
- Site cabins and welfare units
- Temporary fencing and access systems
- Scaffolding equipment
- Vans and commercial vehicles
- Surveying and measurement equipment
- Generators and temporary power units
- Storage yards and depots
- Regional offices
- Specialist equipment for particular projects
- Business/tactical clothing for workforce
Some arrangements may be short-term hire. Others may be longer-term leases. Some may be embedded inside service contracts. The challenge is identifying which contracts contain leases and how they should be accounted for.
Plant Hire Companies: Lessor Considerations
Much of the focus is on lessees, but plant hire companies and equipment lessors also need to understand the changes. Their customers may ask more questions about contract terms, lease components, service components and payment schedules.
While the biggest change under the revised model is for lessees, lessors may still need to maintain accurate classification, documentation and disclosure. They may also find that customers want clearer contract breakdowns to support their own accounting.
Plant hire businesses that can provide transparent lease data may become easier for contractors to work with.
Systems and Data Requirements
For many construction businesses, the hardest part of FRS 102 lease accounting will be data.
A company needs to know:
- What leases exist
- Contract start and end dates
- Payment schedules
- Renewal options
- Break clauses
- Variable payments
- Service components
- Asset descriptions
- Responsible departments
- Project allocation
- Discount rates
- Modifications and extensions
- Terminations
This data may be spread across procurement systems, site teams, emails, plant managers, finance systems and contract files.
A central lease register will be essential. For companies with more than a handful of leases, lease accounting software may be worth considering.
Why Spreadsheets May Struggle
Some construction businesses will try to manage the transition in spreadsheets. That may work for very simple lease portfolios, but construction lease arrangements are often too dynamic.
Common spreadsheet risks include:
- Missing hire agreements
- Incorrect lease terms
- Broken formulas
- Poor version control
- Manual posting errors
- Failure to update modifications
- Weak audit trail
- Incorrect classification
- Inconsistent discount rates
- Poor link to project costing
Construction projects change frequently. Equipment is moved, hired, extended, returned and replaced. A static spreadsheet can quickly become unreliable.
What Construction Finance Teams Should Do Now
Construction finance teams should begin preparing well before the first affected year-end.
A sensible plan includes:
- Build a full lease and hire contract inventory
- Separate short-term hire from longer-term leases
- Review plant, vehicle, property and equipment arrangements
- Identify embedded leases in service contracts
- Agree lease accounting policies with advisers
- Assess short-term and low-value exemptions
- Review likely balance sheet impact
- Model covenant effects
- Update project costing processes
- Train procurement and site teams
- Consider lease accounting software
- Speak to lenders, bonding providers and auditors early
Waiting until accounts preparation will create unnecessary pressure.
Operational Teams Need to Be Involved
This cannot be solved by finance alone. Site managers, plant managers, procurement teams and operations directors often know the real terms and use of leased assets.
Finance may see an invoice. Operations knows whether the item is dedicated to one project, whether the hire is likely to be extended, whether an operator is included, and whether the asset can be substituted.
Those operational facts can affect lease accounting.
A strong process should require significant lease or hire contracts to be reviewed before signing, not months later during the audit.
Construction Examples
A housebuilder leasing site cabins for a multi-year development may need to recognise right-of-use assets and lease liabilities.
A civil engineering contractor leasing specialist tunnelling equipment for a major project may need to assess whether the arrangement is a lease or part of a wider service contract.
A regional contractor leasing vans for supervisors and project managers may need to bring those vehicle leases onto the balance sheet.
A scaffolding business leasing storage yards and commercial vehicles may see both property and fleet leases affected.
A demolition contractor using short-term equipment hire may have a mix of exempt short-term hires and longer arrangements that require recognition.
The practical result is that every construction business needs to review its own contract base rather than relying on generic assumptions.
The Construction Impact Roundup
FRS 102 lease accounting changes will have a significant impact on the UK construction industry because leasing and hiring are central to how construction work is delivered. Plant, equipment, vehicles, depots, site accommodation and temporary assets all need careful review.
For many businesses, the change will mean higher reported assets and liabilities, different profit and loss presentation, more complex project costing and greater scrutiny from lenders, auditors and bonding providers.
The commercial reality of leasing may not change, but the accounting visibility will.
Construction firms that prepare early will be in the strongest position. They will know what leases they have, understand the balance sheet impact, update project reporting, protect covenant discussions and reduce year-end stress.
For an industry where margins are tight and financial control is essential, FRS 102 lease accounting is not just a compliance exercise. It is an opportunity to gain a clearer view of the assets, obligations and costs that underpin every project.